Introduction
A quotation tells your customer what something will cost. An invoice tells them they now owe you for it.
Those two sentences cover 90% of the difference. But in practice — especially for UAE businesses navigating VAT compliance, contract disputes, and client relationships — the details matter considerably more than that summary suggests.
A quotation records proposed terms; an invoice records an amount requested. Whether payment is due depends on the parties' agreement and the underlying supply, not the document label alone. And in the UAE, where the FTA has specific rules about what constitutes a valid tax invoice and when it must be issued, treating these two documents as interchangeable creates compliance problems on top of commercial ones.
This guide explains what each document is, how they differ legally and practically, when to use each one, where the confusion comes from, and how to manage both correctly as a UAE business in 2026.
What Is a Quotation?
A quotation — also called a quote, price quote, or sales quotation — is a formal document a business provides to a potential customer that states the price at which it is willing to supply specific goods or services.
A quotation is an offer, not a transaction. It exists before any money changes hands, before any work begins, and before any legal obligation is created on either side.
Key characteristics of a quotation:
It is conditional. A quotation is valid only for a defined period — typically 7, 14, or 30 days. After that, the business is free to revise the price. The customer cannot hold you to a quote that has expired.
It is not legally binding until accepted. A quotation becomes a binding agreement only when the customer formally accepts it — in writing, by signing, by issuing a purchase order against it, or by instructing you to proceed. Until that point, neither party has any obligation.
It is not a VAT document. A quotation is not a tax invoice. It does not trigger VAT. It does not need to include your TRN in the same way a tax invoice does. It does not need to follow FTA invoice formatting rules.
It sets commercial expectations. A well-written quotation prevents disputes down the line by documenting what was agreed before work started: the scope, the price, what is included, what is not, payment terms, and timelines.
What Is an Invoice?
An invoice is a formal document issued by a supplier to a customer after a supply has been made or agreed, demanding payment for goods delivered or services rendered.
An invoice is a demand for payment, not an offer. It exists after the commercial relationship is confirmed — after the quotation was accepted, after the work was done, or after the goods were delivered.
Key characteristics of an invoice:
It creates a legal payment obligation. Once an invoice is issued and received by the customer, it creates a legal obligation to pay the stated amount by the due date. In the UAE, unpaid invoices can be pursued through the courts and — for commercial disputes above certain thresholds — through formal legal proceedings.
It is a VAT document. For VAT-registered businesses in the UAE, an invoice is a tax invoice. It must comply with FTA requirements, include all mandatory fields, be issued within 14 days of the date of supply, and follow sequential numbering. Missing any of these is a compliance failure.
It is a financial record. Invoices form part of your accounting records and your VAT return data. They are the primary document an FTA auditor will examine to verify your declared output VAT.
It is not revisable once issued. Unlike a quotation — which you can revise freely until it is accepted — an invoice cannot be edited after it is sent. If you made an error, you must issue a credit note and a corrected invoice.
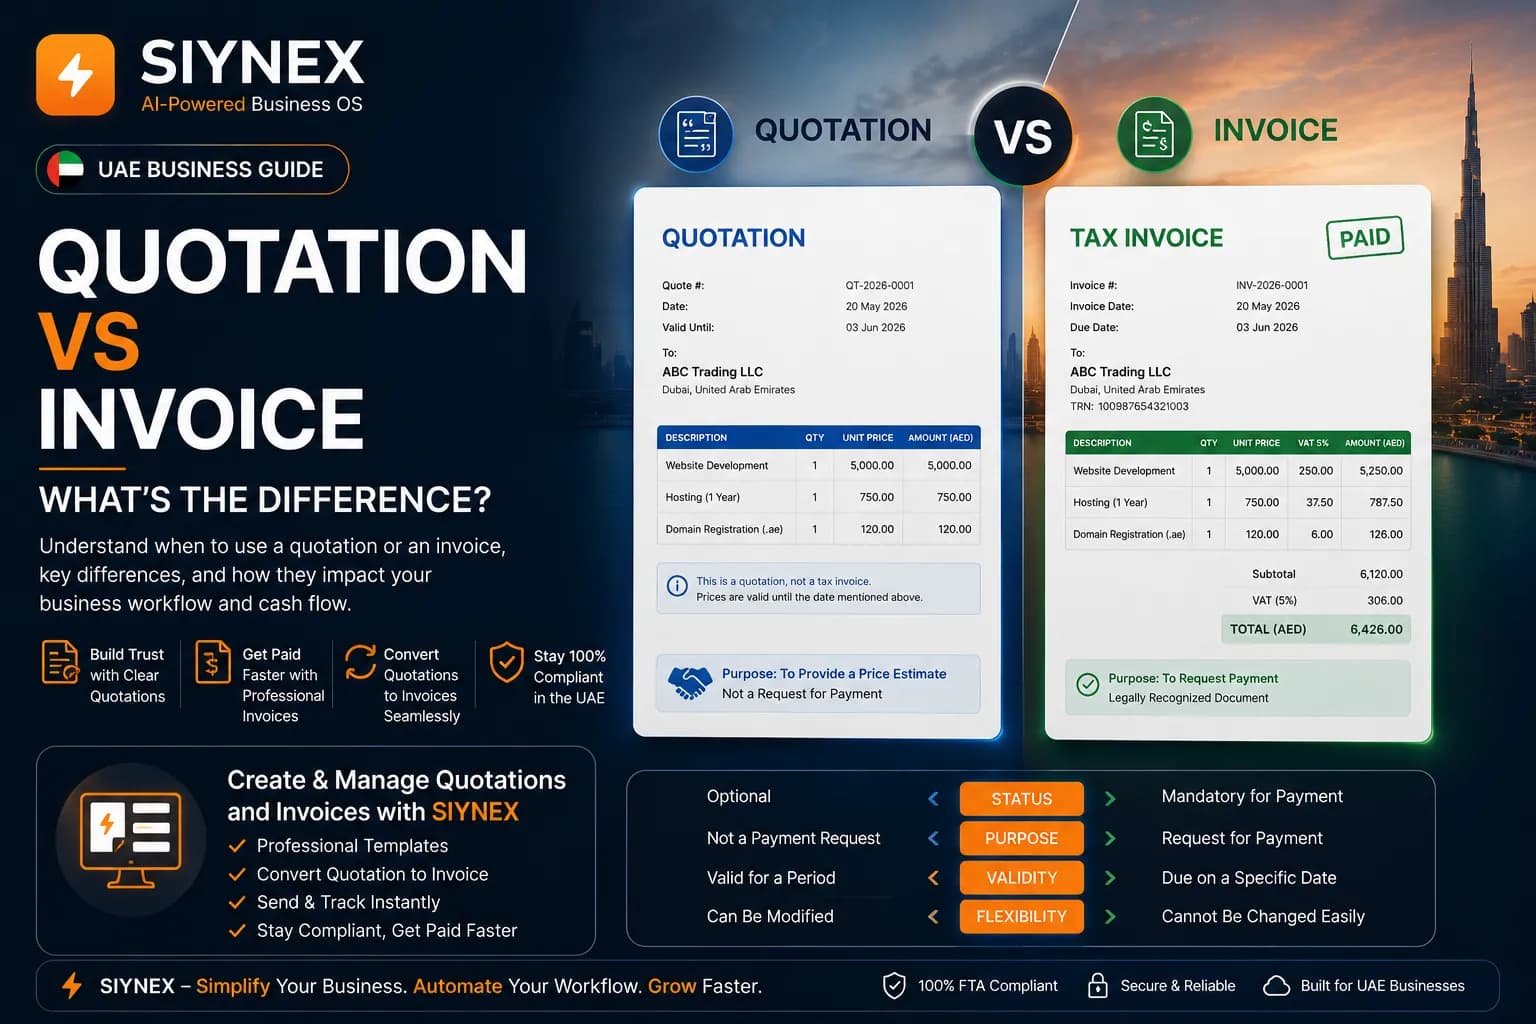
Quotation vs Invoice: Side-by-Side Comparison
- Feature: Purpose — Quotation: Offer a price before the sale — Invoice: Request payment after the supply
- Feature: When issued — Quotation: Before work begins or order is confirmed — Invoice: After delivery or at agreed billing date
- Feature: Legal status — Quotation: Offer — not binding until accepted — Invoice: Request for payment under the underlying transaction
- Feature: VAT implications — Quotation: Not a VAT document — Invoice: Tax invoice subject to FTA rules
- Feature: TRN required — Quotation: Not mandatory (good practice to include) — Invoice: Mandatory for VAT-registered suppliers
- Feature: FTA mandatory fields — Quotation: None specifically — commercial document — Invoice: Applicable FTA tax-invoice particulars
- Feature: Numbered sequentially — Quotation: Recommended but not legally required — Invoice: Legally required, no gaps permitted
- Feature: Can it be edited? — Quotation: Yes, freely until accepted — Invoice: No — requires credit note if incorrect
- Feature: Triggers VAT liability? — Quotation: No — Invoice: Yes — determines your output VAT
- Feature: Expiry date — Quotation: Yes — typically 7–30 days — Invoice: No — due date, not an expiry
- Feature: Used to reclaim input VAT? — Quotation: No — Invoice: Yes — buyers need it for VAT recovery
- Feature: Signed by customer? — Quotation: Often yes, to confirm acceptance — Invoice: Not typically signed
The Document Journey: From Quote to Invoice
Understanding the relationship between these two documents is easier when you see the full commercial cycle:
Step 1 — Quotation sent
You identify a potential customer's requirement and send them a quotation outlining the scope, price, terms, and validity period.
Step 2 — Quotation accepted
The customer formally accepts — by signing, by purchase order, by email confirmation, or by instructing you verbally (though written acceptance is strongly recommended). At this point, a contract exists.
Step 3 — Goods delivered or services performed
You fulfil the obligation created by the accepted quotation.
Step 4 — Invoice issued
You issue a tax invoice for the agreed amount within 14 days of the date of supply. This triggers VAT liability and creates the payment obligation.
Step 5 — Payment received
The customer pays the invoice by the due date. The transaction is complete.
Every step matters. A recorded quotation can help establish agreed terms. A tax invoice is a separate record required where the VAT rules apply; the legal payment claim depends on the underlying agreement and supply.
Where the Confusion Comes From
Most businesses that mix up quotations and invoices are not confused about the definitions — they are cutting corners in a workflow that feels unnecessarily formal, especially for repeat clients or smaller transactions.
Here is where it goes wrong in practice:
Sending an Invoice Before a Quote Was Accepted
You have done a site visit, discussed the job, and the client seemed keen. You send an invoice for the deposit without a signed quotation. The client disputes the price or the scope. You have no written agreement to refer to — just an unpaid invoice.
In the UAE, a contract does not need to be in writing to be valid. But proving the terms of an oral agreement in a commercial dispute is significantly harder than presenting a signed quotation.
Using a Quotation as an Invoice
You send a quotation, the client verbally says "yes," and then nothing else is issued — you wait for payment based on the quotation document. This is common among freelancers and smaller businesses.
The problem: a quotation is not a legal demand for payment. It is an offer. A quotation alone does not establish that an invoiced amount is overdue. You also have no VAT-compliant record for the FTA.
Issuing a "Proforma Invoice" When You Mean a Quotation
This is the most common source of confusion in the UAE. A proforma invoice looks like an invoice — it has an invoice-style layout, shows prices and totals, sometimes even shows VAT — but it is issued before the transaction is confirmed, typically to allow a customer to arrange payment or financing.
A proforma invoice is not a tax invoice. It has no VAT standing with the FTA. A customer cannot use it to reclaim input VAT. It does not trigger your VAT liability. It should be clearly labelled "Proforma Invoice" to avoid being treated as a tax invoice.
The correct sequence: proforma invoice (if needed for the customer's procurement process) → customer confirms and pays → actual tax invoice issued.
Businesses that issue proformas and never follow them with a proper tax invoice are creating a VAT gap in their records.
Sending the Same Document and Calling It Different Things
Some businesses use the same template for both quotations and invoices, just changing the title. This creates serious problems:
- The FTA examines your tax invoices for sequential numbering. If you have sent documents labelled "Invoice" that were actually quotations, your invoice sequence has gaps.
- A document labelled "Invoice" is treated as a tax invoice by the FTA regardless of your intention when sending it.
- A customer who receives a document labelled "Invoice" for work not yet agreed may dispute payment on the grounds that they never accepted a quotation.
Use separate templates, separate numbering sequences, and separate workflows for quotations and invoices.
Proforma Invoice vs Quotation vs Tax Invoice: The Full Picture
Since proforma invoices come up in almost every conversation about this topic, here is a clear three-way comparison:
- Document: Quotation — Purpose: Offer a price before agreement — VAT Standing: None — Legal Payment Claim: No
- Document: Proforma Invoice — Purpose: Indicate expected charges before confirmation — VAT Standing: None — not a tax invoice — Legal Payment Claim: No
- Document: Tax Invoice — Purpose: Demand payment after supply — VAT Standing: Subject to applicable FTA requirements — Legal Payment Claim: Depends on the transaction
All three serve different purposes. None is a substitute for the others. The confusion typically comes from businesses using proforma invoices as a hybrid — a practice that creates ambiguity without the legal protection of either a proper quotation or a tax invoice.
What Should a UAE Business Quotation Include?
While quotations are not subject to FTA mandatory field requirements, a professionally structured quotation protects your business commercially. Every UAE business quotation should include:
Your business details
- Company name and logo
- Registered address
- Contact details
- TRN (good practice, though not mandatory on quotes)
Customer details
- Customer or company name
- Contact person and address
Quotation reference and date
- A unique quotation number (for your own tracking)
- Date of issue
- Validity period (e.g., "This quotation is valid for 30 days from the date of issue")
Scope of supply
- Detailed description of what is included
- Explicit statement of what is NOT included (scope exclusions prevent disputes)
- Quantities or estimated hours where applicable
Pricing
- Unit prices
- Subtotal
- VAT amount (clearly stated as an estimate, since VAT is not yet triggered)
- Total including VAT
Terms and conditions
- Payment terms (e.g., 50% deposit on acceptance, balance on completion)
- Delivery or completion timeline
- What happens if scope changes (variation clause)
- Cancellation terms
Acceptance section
- Space for customer signature, name, date, and position
- Or a reference to your online acceptance process
The more detail in your quotation, the less room for dispute when you issue the invoice.
What a UAE Tax Invoice Must Include
Once the quotation is accepted and the supply is made, the tax invoice must meet FTA requirements. The required particulars are discussed in What Information Must Appear on a UAE Invoice? — but the core requirements are:
- "Tax Invoice" label (exact wording)
- Your business name, address, and TRN
- Sequential invoice number
- Issue date and date of supply
- Customer name, address, and TRN (for B2B)
- Description of goods or services
- Quantity, unit price, and subtotal
- Discount shown separately if applicable
- VAT rate and VAT amount per line item in AED
- Total amount due including VAT in AED
- AED equivalent if invoiced in foreign currency
Issued within 14 days of the date of supply.
Managing Quotations and Invoices Together
Keeping quotations and invoices separate but connected helps a business track what was offered, accepted and billed. In SIYNEX, an accepted quotation can be converted into a draft invoice with linked line items and a reference back to the quotation. Review the invoice details and VAT treatment before issuing it; conversion does not certify tax compliance.
If your business regularly prepares customer quotations, explore how SIYNEX helps you create and manage quotations before converting an accepted quotation into a draft invoice. The separate invoicing workflow covers creating and tracking invoices.
For the product workflow, explore how SIYNEX manages quotations. The separate invoicing workflow covers creating and tracking invoices.
Frequently Asked Questions
Q: Can a customer use a quotation to reclaim VAT?
No. A quotation is not a tax invoice and has no VAT standing with the FTA. Only a compliant tax invoice — issued after the supply is made, containing all mandatory fields — can be used by a customer to reclaim input VAT.
Q: Is a quotation legally binding in the UAE?
A quotation on its own is an offer, not a binding contract. It becomes legally binding when the customer formally accepts it — in writing, by purchase order, by email, or by instructing you to proceed. The acceptance, not the quotation itself, creates the contract.
Q: Do I need to include my TRN on a quotation?
It is not legally required by the FTA on quotations, since a quotation is not a tax document. However, including your TRN on quotations is good professional practice and signals to potential customers that you are VAT-registered — which matters to businesses who will want to reclaim input VAT on the eventual invoice.
Q: What is the difference between a proforma invoice and a quotation?
Both are pre-transaction documents with no VAT standing. A quotation is typically used earlier in the sales process as a price offer. A proforma invoice is usually issued later — after informal agreement but before formal confirmation — often for the customer to use in their internal purchase approval or payment process. Neither is a tax invoice. Neither creates a legal payment obligation.
Q: Can I convert a quotation directly into an invoice?
Yes — and you should. The cleanest workflow is to create the invoice based on the accepted quotation, inheriting all line items and prices. This eliminates transcription errors and maintains a clear link between the agreed scope and the final payment demand. SIYNEX does this in one step.
Q: What happens if I issue an invoice for work the customer claims they never agreed to?
This is the commercial risk of invoicing without a signed quotation. In the UAE, contract disputes between businesses are handled through civil courts or the DIFC/ADGM courts depending on jurisdiction. The burden of proving an agreement existed and at what price falls on you as the supplier. A signed or digitally accepted quotation is your strongest evidence. Without it, you are relying on email chains, call records, or witness accounts — a much weaker position.
Q: How long should I keep quotations?
The FTA's 5-year record retention requirement applies to tax invoices and VAT records. Quotations are not specifically covered by FTA rules, but they are commercial records that support your invoices. Best practice is to retain them for the same 5-year period — and indefinitely for any quotation that was the subject of a dispute.
Summary
A quotation presents proposed terms; an invoice requests payment. The two documents serve different stages of a transaction. Keep the accepted terms and invoice records connected, and check the applicable VAT requirements before issuing a tax invoice.
SIYNEX supports accepted-quotation conversion to a draft invoice for review. It does not replace legal or tax advice.
Last reviewed: 24 September 2026 | This article is for informational purposes and reflects UAE commercial and VAT law as of the publication date. For legal or tax advice specific to your business, consult a UAE-registered legal advisor or tax agent.