Introduction
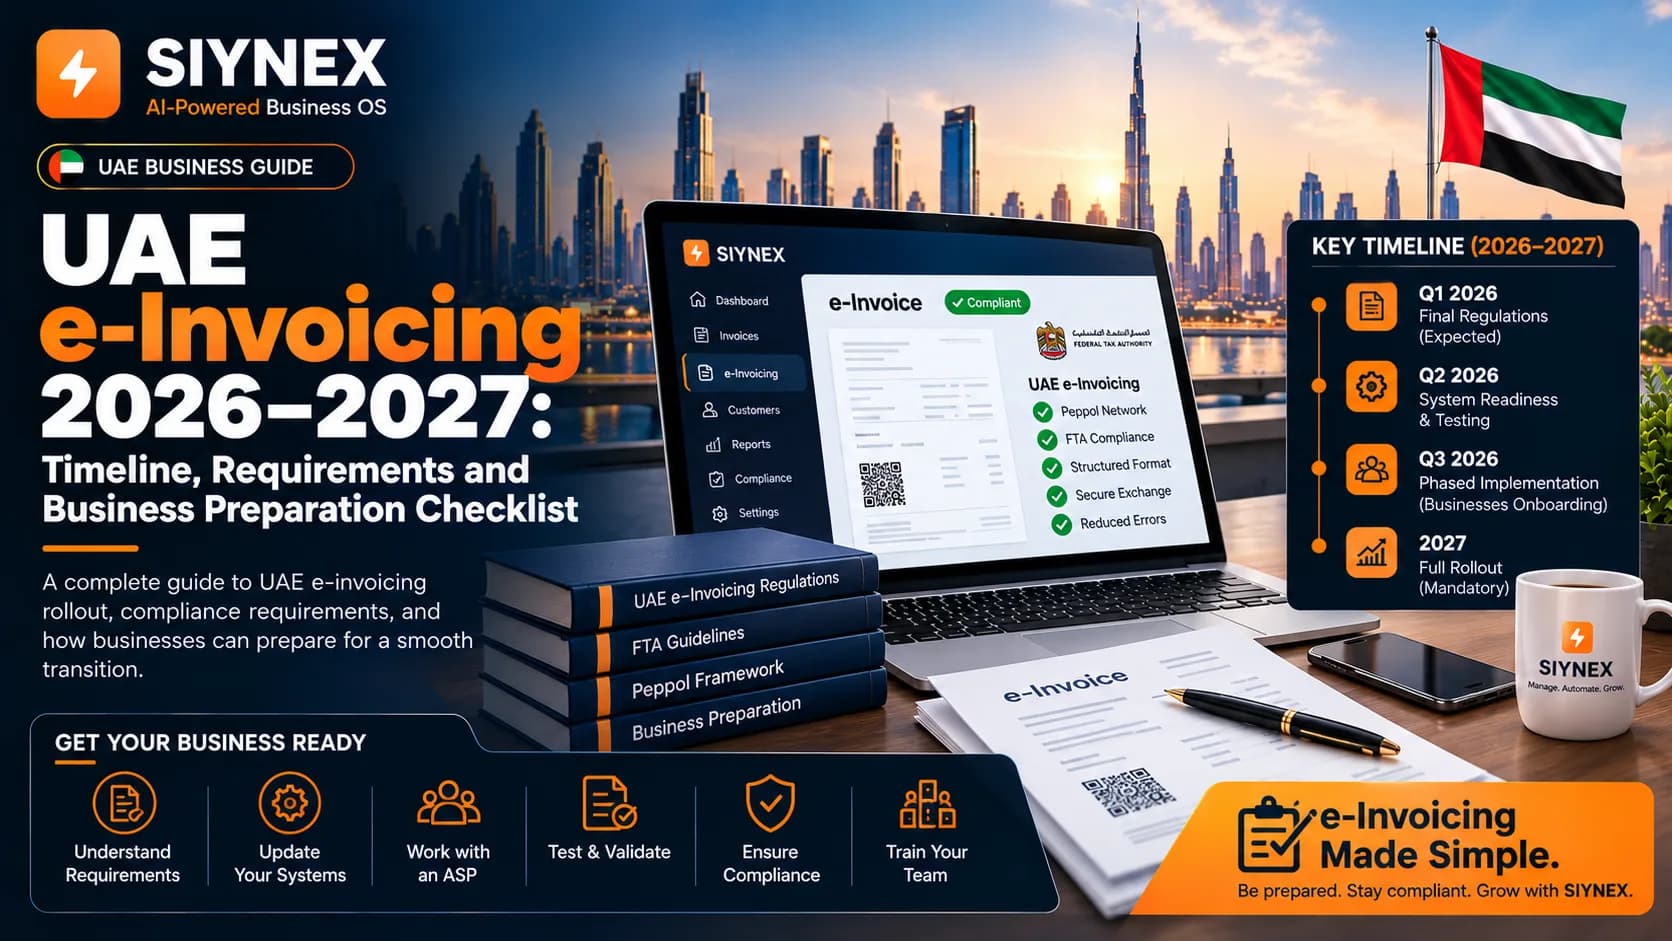
The UAE Electronic Invoicing System introduces structured invoice exchange and tax-data reporting through UAE Accredited Service Providers. It is separate from creating or emailing a PDF invoice. Mandatory implementation begins in phases from 2027, while pilot and voluntary participation began on 1 July 2026.
This guide summarises official rules and guidance available on 14 October 2026. The programme continues to evolve, so confirm operational decisions against the Ministry of Finance eInvoicing portal and obtain professional advice where needed.
What Is a UAE eInvoice?
An eInvoice is structured invoice data issued, exchanged and reported electronically through the UAE Electronic Invoicing System. PDF files, Word documents, images, scanned copies and invoices sent by email are not structured eInvoices.
The official exchange format is XML under the UAE PINT-AE specification. A supplier may submit invoice data to its Accredited Service Provider in another format agreed with that provider, but the provider converts it to the required UAE XML format for provider-to-provider exchange. Official structured eInvoices do not feature a QR code or barcode.
Who and Which Transactions Are in Scope?
Electronic Invoicing applies to persons conducting business in the UAE in respect of business transactions, regardless of VAT-registration status, unless a specific exclusion applies. The general scope includes business-to-business, business-to-government, government-to-business and government-to-government transactions.
Transactions involving a natural person who is not conducting business are outside the current scope. This means business-to-consumer transactions remain excluded until a later ministerial decision. A customer's tax-registration or eInvoicing-onboarding status does not remove an in-scope supplier's obligations.
Non-UAE-established persons can also be in scope where they must issue UAE tax invoices. An investment holding company with only passive income and no business transactions may be outside scope, while recharges or other business transactions can bring relevant activity into scope.
Current exclusions and transitional treatment
Official guidance identifies exclusions including qualifying sovereign government activities, certain airline passenger and ancillary transactions, and specified exempt financial services. Imports of concerned goods and concerned services handled under the VAT reverse-charge rules are not subject to Electronic Invoicing requirements. Other exclusions may be added by ministerial decision.
Business transactions between members of the same VAT group have a temporary 24-month grace period beginning on 1 January 2027. This changes the timing for those intra-group transactions; it does not permanently remove them from scope. Other transactions conducted by the same VAT-group members remain subject to the applicable rules and implementation phase.
Because exclusions are fact-specific, businesses should confirm their position using current Ministry and FTA guidance.
UAE eInvoicing Timeline
- Pilot and voluntary implementation: began on 1 July 2026. Voluntary participants must follow the technical requirements, but the administrative penalties described below apply only from their mandatory implementation date.
- Persons with annual revenue of AED 50 million or more: appoint a UAE Accredited Service Provider by 30 October 2026 and implement by 1 January 2027.
- Persons with annual revenue below AED 50 million: appoint a provider by 31 March 2027 and implement by 1 July 2027.
- In-scope government entities: appoint a provider by 31 March 2027 and implement by 1 October 2027.
The 30 October 2026 date reflects Ministerial Resolution No. 66 of 2026, which extended the earlier appointment deadline for the first mandatory phase. Check the official portal for any later amendment.
How the UAE Five-Corner Model Works
The UAE uses a Decentralised Continuous Transaction Control and Exchange model built on OpenPeppol. The five corners are the supplier, the supplier's Accredited Service Provider, the buyer's Accredited Service Provider, the buyer and the government reporting component.
Each in-scope person generally appoints one UAE Accredited Service Provider for both sending and receiving eInvoices. Onboarding is initiated through EmaraTax. A person already registered with the FTA uses the first 10 digits of its TRN as its TIN; an in-scope person without an existing tax registration must obtain a TIN through EmaraTax. The Peppol participant identifier uses the UAE scheme prefix with that TIN.
Accredited Service Providers
Businesses should select a provider from the current Ministry of Finance accredited list, enter into the required commercial arrangement and allow time for onboarding, integration and testing. Accounting or invoicing software may connect with an accredited provider, but producing PDFs or claiming general “Peppol readiness” does not establish UAE compliance.
Ministerial Decision No. 168 of 2026 introduced an updated accreditation framework effective from 1 October 2026. It repealed the earlier Ministerial Decision No. 64 of 2025 and its amendments, removed the former pre-approval stage and moved providers to direct accreditation after the required evaluation and testing. It also permits defined use of third-party Peppol products and outsourcing while the accredited provider remains responsible for compliance and service delivery. See the official accreditation update.
Documents, Timing and Credit Notes
The framework covers electronic tax invoices, commercial invoices, tax credit notes and commercial credit notes. Electronic Invoicing requirements are distinct from VAT tax-invoice requirements. Where VAT law requires a tax invoice or tax credit note, an in-scope person must issue it in the required structured electronic form.
For VAT registrants, the VAT-law issuance timeline applies. Subject to that rule, Ministerial Decision No. 243 of 2025 generally requires an electronic invoice or electronic credit note to be issued and transmitted within 14 days of the business transaction.
An electronic credit note is required in circumstances including cancellation, a reduction in agreed consideration, a full or partial refund, or correction of an administrative or numerical error. Self-billing and agent-issued documents are possible only under the applicable conditions.
The Ministry publishes mandatory field requirements and PINT-AE specifications for different invoice scenarios. Businesses should map their data and transaction types with their provider instead of treating a generic field list as universal.
Storage and Retention
Official guidance states that data relating to issuing, transmitting and receiving electronic invoices must generally be retained for:
- Taxable persons: five years following the tax period to which the data relates.
- Other persons: five years from the end of the calendar year in which the document was created.
- Real-estate records: seven years from the end of the calendar year in which the document was created.
Additional retention can apply during an FTA dispute or audit and in certain voluntary-disclosure circumstances. Records and associated data must remain secure, complete, readable, reproducible and promptly retrievable by the FTA. The official guidance explains that compliant storage infrastructure may be located inside or outside the UAE if those integrity and retrieval requirements are met.
Administrative Penalties
Cabinet Decision No. 106 of 2025 establishes penalties for persons required to implement the system. Current published amounts include:
- AED 5,000 for each month or part of a month of delay in implementing the system or appointing an Accredited Service Provider within the required timeframe.
- AED 100 for each electronic invoice not issued and transmitted within the required timeframe, capped at AED 5,000 per calendar month.
- AED 100 for each electronic credit note not issued and transmitted within the required timeframe, capped at AED 5,000 per calendar month.
- AED 1,000 for each day or part of a day of delay in a required issuer or recipient notification to the FTA about a system failure.
- AED 1,000 for each day or part of a day of delay in notifying the appointed provider about required changes to data registered with the FTA.
Voluntary participants are not subject to these administrative penalties until the date on which mandatory implementation applies to them. See the official penalty announcement and confirm the prescribed notification timelines before relying on this summary.
Preparing for UAE eInvoicing
SIYNEX Product Scope
SIYNEX currently supports conventional invoice records and PDFs. A PDF is not a structured eInvoice under the UAE programme. Accredited-service-provider connectivity, PINT-AE structured transmission and FTA tax-data reporting have not been verified as available SIYNEX product capabilities. Businesses preparing for the mandate should confirm their obligations and provider arrangements using official Ministry guidance.
Frequently Asked Questions
Is emailing a PDF a UAE structured eInvoice?
No. PDFs, Word files, images, scans and email are unstructured formats and are not eInvoices under the UAE system.
Does the system apply only to VAT-registered businesses?
No. The official scope applies to persons conducting business in the UAE regardless of VAT-registration status, subject to transaction scope, exclusions and implementation dates.
Are consumer transactions currently included?
No. Transactions involving consumers who are not conducting business remain outside the current mandatory scope until a later decision.
Can a business use more than one provider?
The current guidance states that each person or government entity should onboard with one Accredited Service Provider for its sending and receiving requirements.
Does structured eInvoicing replace VAT returns?
No current rule removes existing VAT return obligations merely because structured invoice data is exchanged and reported. Continue following current FTA filing requirements.
Does SIYNEX currently transmit UAE structured eInvoices?
No verified accredited-provider integration, PINT-AE transmission or FTA reporting capability is available in the current SIYNEX product. Conventional invoice creation and PDFs are separate workflows.
Summary
UAE Electronic Invoicing is a structured exchange and reporting system operating through Accredited Service Providers. Current mandatory implementation begins on 1 January 2027 for persons with annual revenue of AED 50 million or more, followed by smaller persons and government entities later in 2027. Scope is broader than VAT registration alone, and current rules include transaction exclusions, provider obligations, data requirements, retention periods and administrative penalties.
Use this article as a preparation overview. Confirm the latest position on the official Ministry of Finance eInvoicing portal before making compliance or implementation decisions.
Regulatory review: 14 October 2026. This article is general information and does not constitute tax or legal advice.